Bundling Home and Auto Insurance in Temple, TX: What You Save
Home and auto insurance bundle in Temple, TX: what the savings look like
If you're paying two separate bills to two separate insurance companies for your home and auto coverage, you're almost certainly leaving money on the table. Bundling your home and auto insurance in Temple, TX is one of the fastest ways to lower both premiums without cutting coverage. Most carriers offer a multi-policy discount of 10% to 25% when you combine these two policies with the same company, and in a Texas market where homeowners premiums have climbed sharply over the past few years, that discount can translate to real dollar savings every month.
How a bundle discount actually works
When you carry both your homeowners policy and your auto policy with the same insurance company, that carrier rewards you with a discount on each policy. The math works in both directions. Your home premium drops, and your auto premium drops. Some carriers apply the discount evenly; others weight it more heavily toward one policy. Either way, the combined effect is a lower total insurance spend for the same amount of protection.
Consider a realistic example. A Temple homeowner paying $2,400 a year for homeowners insurance and $1,600 a year for auto insurance is spending $4,000 total. A 15% bundle discount applied to both policies brings that down to roughly $3,400 a year , a savings of about $600 annually without changing a single coverage limit. Over five years, that's $3,000 back in your pocket just for consolidating carriers.
The actual discount you receive depends on the carrier, your claims history, the age of your home, your vehicles, and your credit score. Texas allows carriers to use credit-based insurance scores in their pricing, so a strong credit profile can amplify your bundle savings even further.
Why Temple, TX homeowners should pay attention to their home coverage
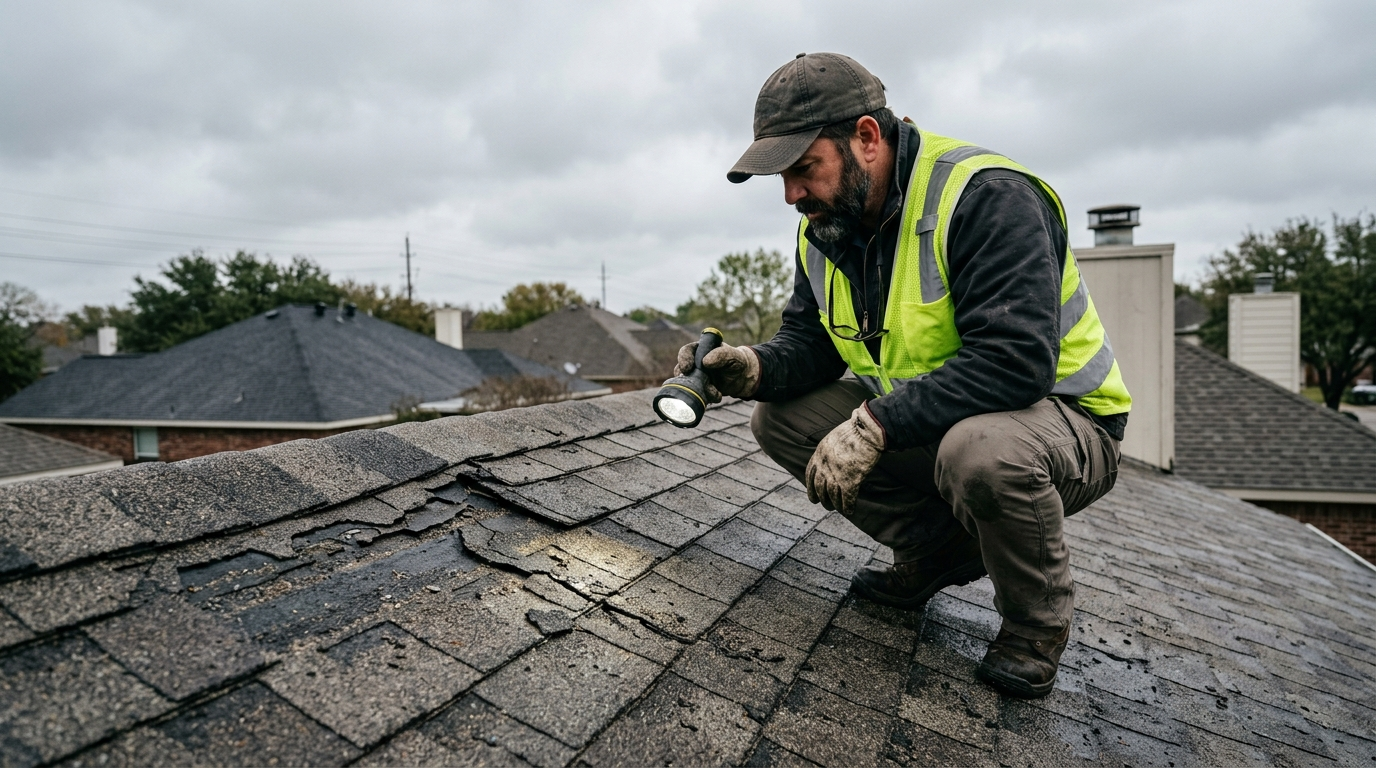
Temple sits in Bell County in Central Texas, where the weather is reliably severe. Hail storms roll through the region with regularity, and the area sees its share of thunderstorms, high winds, and the occasional tornado. Homeowners in Temple know that a solid homeowners insurance policy is a necessity, not a luxury.
What makes bundling especially worthwhile in this market is that Texas homeowners have seen significant premium increases over the past three years. Carriers have adjusted their rates upward in response to increased claims volume from hail and wind events. Finding any legitimate discount mechanism matters more now than it did five years ago. A bundle discount is one of the few levers you can pull without reducing your coverage.
If you've already been shopping around for more affordable car insurance in Temple, it's worth running the numbers on your home policy at the same time. Treating the two searches separately often costs you money compared to approaching both policies together through an independent agent who can shop multiple carriers at once.
What a bundle typically includes and what to watch for
A standard home and auto bundle means your homeowners policy and your personal auto policy are both placed with the same carrier. Bundling does not have to stop there, though. Many carriers extend the multi-policy discount when you add lines such as:
- Umbrella insurance adds a liability layer above both your home and auto policies, and often qualifies for its own discount when bundled.
- Motorcycle insurance can extend the discount if you ride.
- RV or trailer coverage is commonly included in bundle pricing, since Central Texas has a large population of RV owners.
- Boat or watercraft insurance is worth checking if you keep a boat on Stillhouse Hollow Lake or Belton Lake.
One thing to watch: a bundle discount does not automatically mean you're getting the best total price. If one carrier offers a 20% bundle discount but its base rates are significantly higher than a competitor's, you could still end up paying more than if you placed each policy with a different carrier at a competitive base rate. This is where working with an independent agent matters. An independent agent can compare bundled pricing across multiple carriers, not just present one company's bundle offer.
Bundling versus keeping policies separate: when split coverage makes sense
There are situations where keeping policies with different carriers is the right call, even if it means forgoing the bundle discount. The scenarios worth discussing with your agent include:
- High-risk driver in the household. If someone on your auto policy has recent at-fault accidents or a DUI, your auto premium with any given carrier may be high enough that the bundle discount does not offset the surcharge. A specialty auto carrier with no bundle option may price that risk better overall.
- Older home with prior claims. Some carriers that offer competitive auto rates have restrictive home underwriting guidelines for older homes or homes with prior water damage claims. You may need a different home carrier even if it costs you the bundle discount.
- Specialty home coverage needs. If your home's replacement cost exceeds standard carrier caps, or you need extended replacement cost coverage after a storm pushes your policy limits, a surplus lines or specialty home carrier may be required regardless of the bundle math.
These are the conversations you cannot have with a captive agent who represents only one company. An independent agent can walk through all of these scenarios and show you the actual numbers.
Discounts that stack on top of a bundle
The bundle discount is often just the starting point. Texas homeowners and drivers can layer additional discounts on top of the multi-policy discount to bring premiums down further. Common stackable discounts include:
- Claims-free discount. Carriers reward policyholders who have not filed claims in three to five years with a loyalty or loss-free discount on both home and auto.
- New home discount. Homes built within the last five to ten years typically qualify for a new construction credit that reduces homeowners premiums.
- Roof age credit. A newer roof (generally under ten years old) can meaningfully reduce your homeowners premium in Texas, where hail claims drive much of carrier loss exposure.
- Safe driver discount. Clean driving records over three to five years qualify for credits on the auto side.
- Telematics or usage-based programs. Several carriers offer programs where you allow the company to monitor driving behavior through an app or device, and safe drivers earn additional credits.
- Home safety features. Monitored alarm systems, deadbolts, smoke detectors, and fire suppression systems all generate small home credits that compound with the bundle.
A well-shopped bundle that stacks several of these discounts can bring your combined home and auto premium well below what you'd pay carrying each policy separately with different carriers. For a closer look at home-specific savings, the post on home insurance discounts in Texas breaks down the credits carriers commonly offer Texas homeowners.
What to bring when you shop for a bundle in Temple
Getting an accurate bundle quote is faster when you come prepared. An agent will need the following to quote both policies at once:
- Property information. Your home's year built, square footage, construction type (frame, brick veneer, masonry), roof material, and year the roof was last replaced.
- Current coverage details. Your existing homeowners declarations page showing current limits and deductibles.
- Vehicle information. Year, make, model, and VIN for every vehicle in the household.
- Driver information. Names, dates of birth, and license numbers for all household drivers, plus any accidents or violations in the past five years.
- Current auto declarations page. Your existing auto policy showing current liability limits, comprehensive and collision deductibles, and any endorsements you carry.
With that information in hand, an independent agent can typically run bundle quotes across multiple carriers in a single appointment and give you a side-by-side comparison of what your total annual spend looks like with different combinations.
Get your home and auto bundle quote in Temple, TX
Winkler Insurance Agency is an independent insurance agency serving Temple and the surrounding Bell County area, including Belton, Killeen, Harker Heights, and Copperas Cove. As an independent agency, Winkler does not work for one insurance company. The team shops multiple carriers on your behalf to find the combination that gives you the best coverage at the lowest total cost, whether that means a bundle with one carrier or the best individual policies across different companies.
If you're paying too much for home and auto coverage separately, or if you haven't compared your current bundle against the market in a few years, now is a good time to take a fresh look. Rates have shifted, and the carrier that was the best fit three years ago may not be the best option today. You can reach the team directly at 254-771-5600 to talk through your options.
Contact Winkler Insurance Agency to get a bundled home and auto quote and see how much you could save by consolidating your coverage under one agency.
Get A Quote
At Winkler Insurance Agency, securing your future is simple. Ready to protect what matters? Contact us for a quick quote!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.