Home Insurance Discounts in Texas: Lower Your Premium Now Guide

September 18, 2026

Home insurance discounts in Texas: what actually lowers your premium

Home insurance discounts in Texas are not a marketing gimmick. They are real, contractual reductions built into carrier rate filings, and most homeowners in Central Texas leave them on the table simply because nobody walked them through the list. If your premium has crept up over the past few renewals, there is a good chance you qualify for savings you are not receiving yet.

Texas is one of the most expensive states in the country for homeowners insurance. Carriers price for hail, wind, wildfire exposure, and litigation costs all at once, so the baseline rate is high before any adjustments apply. That makes knowing how to lower your home insurance premium here more consequential than it would be in, say, Ohio. A 10 percent discount on a $3,200 annual premium is $320 back in your pocket every year.

The bundling discount: the biggest single reduction available

Carriers compete hard for customers who give them multiple policies. When you combine your home and auto with the same insurer, the discount typically runs 5 to 20 percent off the home premium , and you usually pick up a smaller reduction on the auto side too. Some carriers add further savings if you include a life policy or an umbrella.

The math is straightforward. If your homeowners premium is $2,800 and the bundling discount is 12 percent, that is $336 saved annually. Add a modest auto discount of 5 percent on a $1,400 auto policy and you save another $70, for a total of over $400 per year.

One caveat: bundling is only a real deal if the combined premiums at the same carrier beat the combined premiums at separate carriers. An independent agency can run that comparison before you commit, which is exactly what we do at Winkler Insurance Agency. You can read more about how this works in our guide to bundling home and auto in Texas.

Home protection features that carriers reward

Insurance pricing is rooted in risk. Anything that makes your home less likely to produce a claim, or that reduces the size of a claim when one does occur, is something a carrier will often reward with a lower rate.

Alarm and monitoring systems

A centrally monitored burglar and fire alarm system can earn a discount of 2 to 15 percent depending on the carrier and the level of monitoring. Basic smoke detectors get you something; a professionally installed, UL-listed system with 24/7 central station monitoring gets you considerably more. Smart home devices that detect water leaks early are also beginning to earn credits with several carriers.

Roof age and material

In Central Texas, the roof is the single most scrutinized component of your home from an underwriting standpoint. Hail is a year-round threat in Bell County, McLennan County, and the surrounding areas. Carriers will often charge significantly less for a newer roof, and some offer additional credits for impact-resistant roofing materials with a Class 4 UL 2218 rating. A Class 4 roof can earn a discount of 15 to 30 percent with certain carriers. If your roof is approaching 10 years old, it is worth asking what a replacement would do to your premium before the carrier starts pricing in the age penalty.

Sprinkler systems

Whole-home fire sprinkler systems are uncommon in existing residential construction but standard in many newer custom builds. If your home has one, most carriers will reward it with a discount of 5 to 15 percent .

Storm shutters and wind mitigation features

Homes with reinforced garage doors, hip roofs, or other construction features that reduce wind damage may qualify for wind mitigation credits. This is more formalized in coastal Texas through wind inspections, but some inland carriers factor construction type and storm-hardening features into their rates as well.

Loyalty, claims-free, and other behavioral discounts

Carriers want to retain good customers. Most offer a discount that grows the longer you stay with them, often starting after three years and increasing at five. The typical loyalty credit runs 3 to 10 percent .

A claims-free history is also rewarded. If you have not filed a claim in three to five years, many carriers will reduce your rate through what is sometimes called a "preferred customer" or "loss-free" discount. The inverse is also true: filing a small claim can cost you more in rate increases over three to five years than the claim was worth. This is a conversation worth having with your agent before you file.

Some carriers offer discounts for:

  • Age of the insured , retirees or homeowners 55 and older often qualify for a senior discount, since statistically they spend more time at home and catch problems earlier.
  • New purchase , if you just bought the home, some carriers offer a discount for new homeowners in the first year.
  • Higher deductible , choosing a higher all-peril deductible lowers your premium because you are absorbing more of the small-claim risk yourself. This is separate from your wind and hail deductible, which in Texas is often expressed as a percentage of your dwelling coverage (commonly 1 to 2 percent of Coverage A) rather than a flat dollar amount.
  • Paperless and autopay , small but easy: many carriers reduce your premium by 1 to 2 percent if you go paperless and set up automatic payment.

Coverage decisions that affect price (without cutting corners)

There is a difference between reducing coverage to save money and structuring coverage intelligently so you are not paying for things that do not serve you. The latter is smart; the former is a trap.

Dwelling coverage amount

You should insure your home for its replacement cost , not its market value. In many parts of Central Texas right now, construction costs per square foot are higher than they were five years ago. Underinsuring your home to cut your premium is one of the most common and costly mistakes Texas homeowners make. If you want to explore what the right coverage amount looks like, our post on how much homeowners insurance you need in Texas goes into detail.

Coverage for detached structures, personal property, and loss of use

Most policies set detached structure coverage (Coverage B) at 10 percent of dwelling coverage automatically. If you have a modest fence and no other structures, you may not need that much. Personal property (Coverage C) can often be adjusted based on what you actually own. Loss of use (Coverage D) is harder to trim without creating real exposure. These are the items to review with your agent rather than accepting the defaults.

Flood and wind coverage are not part of the standard policy

Texas homeowners policies exclude flood damage entirely. If you are in a flood-prone area near the Little River, the Leon River, or any creek system in the Bell or Coryell County area, you need a separate flood policy. The National Flood Insurance Program (NFIP) is the primary option, though private flood carriers are available and worth comparing. Adjusting your flood policy deductible or coverage structure is a separate matter from your home policy discount strategy. Our guide to flood insurance in Central Texas covers the details.

What to do at renewal to make sure you are getting every discount

Most homeowners review their insurance once at purchase and then auto-renew without a second look. The carrier is not going to call you and volunteer discounts you have not asked about. A practical checklist to run through every year at renewal:

  • Confirm your roof age and material , if your roof is newer or you upgraded to a Class 4 shingle, make sure the carrier has it documented.
  • Report new security systems , if you added a Ring Alarm with professional monitoring or a SimpliSafe system since your last renewal, notify the carrier.
  • Review your deductible levels , if your financial situation has improved and you can comfortably absorb a higher all-peril deductible, the premium savings may be worth it.
  • Ask about bundling , if your auto is with a different carrier, get a bundle quote. The market shifts every year and the math may work now even if it did not two years ago.
  • Check your claims history report , carriers use the CLUE (Comprehensive Loss Underwriting Exchange) report. Make sure it only shows claims you actually filed and that nothing is attributed to your address from a previous owner.
  • Ask specifically about every discount the carrier offers , request the full list, not just the ones the system applies automatically.

Why working with an independent agency changes the math

A captive agent works for one company and can only offer discounts that company has filed with the Texas Department of Insurance (TDI). An independent agent works with multiple carriers and can shop your risk across several companies at once. If Carrier A does not reward your Class 4 roof heavily but Carrier B does, you end up at Carrier B. If Carrier C offers the best bundle deal for your specific combination of home and vehicle, you go there.

Texas home insurance rates are not regulated the way auto rates are in some states. Each carrier sets its own base rates and discount schedules, and those schedules differ significantly from company to company. The best discount structure depends on your specific home, location, claims history, and coverage needs. Because there is no universal answer, access to multiple carriers through an independent agent matters. You can read more about how this works in our post on independent vs. captive agents in Texas.

Shopping your policy does not mean switching every year. It means making sure you are with the right carrier for your current situation and that the carrier has all the information it needs to apply every discount you have earned.

Get a second opinion on your home insurance rate

Winkler Insurance Agency is an independent insurance agency serving Temple, Killeen, Belton, Waco, Harker Heights, and the surrounding Central Texas communities. We work with multiple carriers, which means we compare rates and discount structures on your behalf rather than steering you toward one company's product.

If you have not had your homeowners policy reviewed in the past year, or if your premium went up at renewal and nobody explained why, give us a call at 254-771-5600 or reach out through our contact page. We will look at what you are paying now, what discounts you may be missing, and whether a different carrier offers a better fit for your home and budget. No pressure, just a straight comparison.

Telephone icon with speech bubble.

Get A Quote

At Winkler Insurance Agency, securing your future is simple. Ready to protect what matters? Contact us for a quick quote!

Black telephone handset icon.

Kelly

Speak to Kelly 24/7

Microphone icon.

Microphone ready


Black checkmark.

Start your custom insurance quote

Black checkmark on a white background.

Instant answers to your insurance questions

Black check mark.

Schedule appointments or follow-ups

Person holding a shield with a check mark, representing protection or security.

Personal Insurance

From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.

Buildings, coins with dollar sign, and shield with checkmark; financial security concept.

Commercial Insurance

We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.

Share this article

Recent Posts

A single-story brick home and a parked car in a Temple, Texas neighborhood on a sunny afternoon
By Winkler Insurance Agency • November 1, 2026
See how bundling home and auto insurance in Temple, TX can save you hundreds a year. Winkler Insurance Agency shops multiple carriers to find your best deal.
Apartment balcony in a Round Rock Texas residential complex on a sunny afternoon
By Winkler Insurance Agency • October 29, 2026
Need renters insurance in Round Rock, TX? Learn what's covered, what it costs, and how to protect your belongings. Get a quote from Winkler Insurance Agency.
Cozy apartment living room with moving boxes and personal belongings in Harker Heights Texas
By Winkler Insurance Agency • October 26, 2026
Learn what renters insurance covers in Harker Heights, TX, how much it costs, and why local renters need it. Get a free quote from Winkler Insurance Agency.
Cozy furnished Texas vacation rental home with a covered porch and blue sky, ready for short-term guests
By Winkler Insurance Agency • October 23, 2026
Renting on Airbnb or VRBO in Texas? Learn why standard homeowners policies fall short and how to get the right short-term rental insurance coverage.
Exterior of a Texas brick rental house with a for rent sign in the front yard on a sunny afternoon
By Winkler Insurance Agency • October 20, 2026
Texas landlords: learn what rental dwelling insurance covers, what it excludes, and how to set the right limits. Get quotes from Winkler Insurance Agency today.
Texas homeowner speaking with an insurance adjuster outside a storm-damaged house with hail-dented roof shingles
By Winkler Insurance Agency • October 17, 2026
Learn how the homeowners claims process works in Texas, from filing to settlement. Winkler Insurance Agency helps Central Texas homeowners get it right.
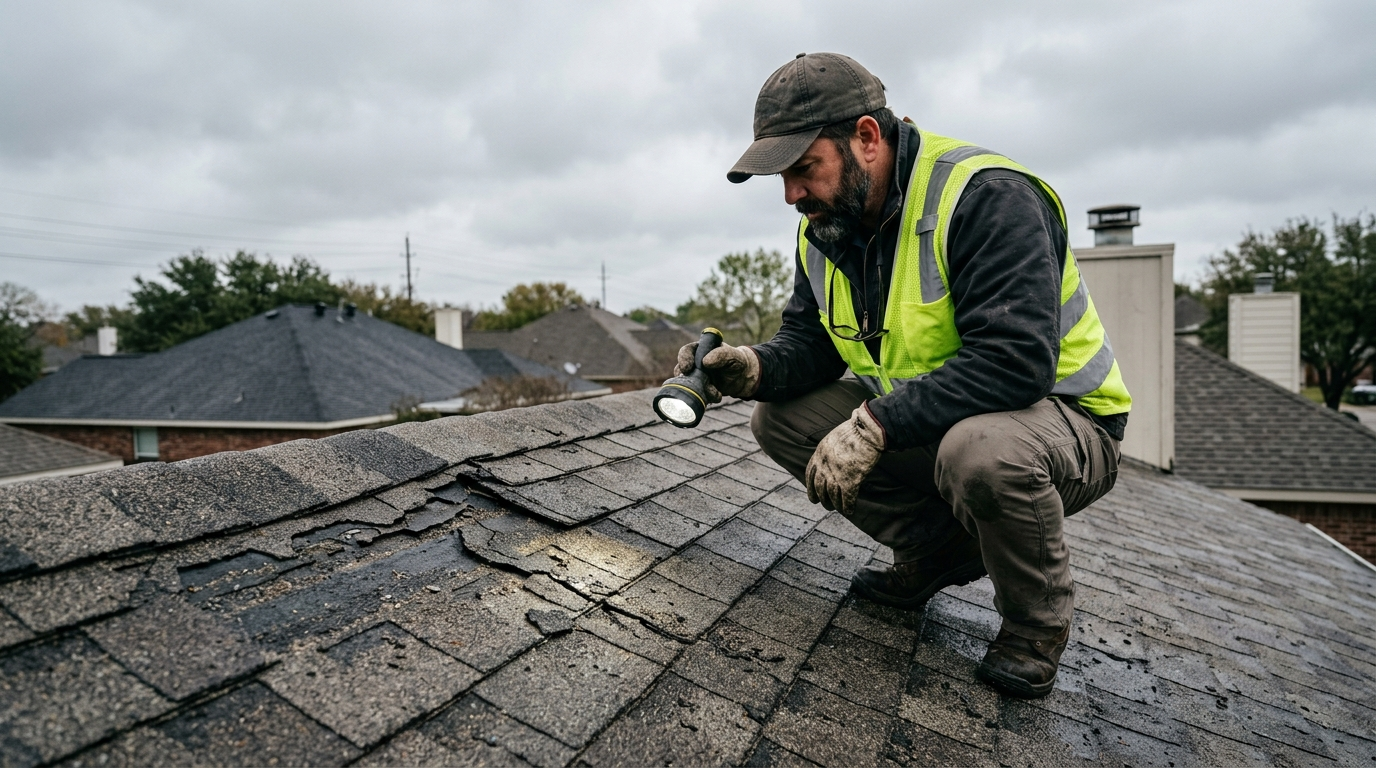
Closeup of hail-damaged asphalt shingles on a Central Texas home roof after a storm
By Winkler Insurance Agency • October 14, 2026
Learn how to file a roof damage claim in Texas, avoid common denials, and protect your Central Texas home. Winkler Insurance Agency explains every step.
A rideshare driver in a sedan at a Central Texas intersection, phone mounted on dashboard showing a rideshare app
By Winkler Insurance Agency • October 11, 2026
Driving for Uber or Lyft in Texas? Learn how rideshare insurance fills the coverage gap and covers you in all phases. Get quotes from Winkler Insurance Agency.
A Texas driver's license and car keys resting on a courthouse counter with paperwork visible in the background
By Winkler Insurance Agency • October 8, 2026
Need SR-22 insurance in Texas? Learn who needs it, how much it costs, and how long you carry it. Winkler Insurance Agency shops multiple carriers for you.
Aerial view of a busy highway interchange in Round Rock, Texas on a sunny afternoon
By Winkler Insurance Agency • October 5, 2026
Need car insurance in Round Rock, TX? Learn what coverage you need, what drives rates locally, and how to compare. Get help from Winkler Insurance Agency.