Home Insurance in Belton, TX: What Every Homeowner Needs in Texas
Home insurance in Belton, TX: what every homeowner needs to know
If you own a home in Belton, home insurance in Belton, TX is not just a mortgage requirement. It is the financial protection behind everything you have built. Belton sits in Bell County, where Central Texas weather can shift from a calm spring afternoon to a severe hailstorm or tornado watch within hours. Add in the proximity to Lake Belton and the region's rapid growth, and your coverage picture is more nuanced than any standard online quote tool will capture.
Why Belton homeowners face unique risks
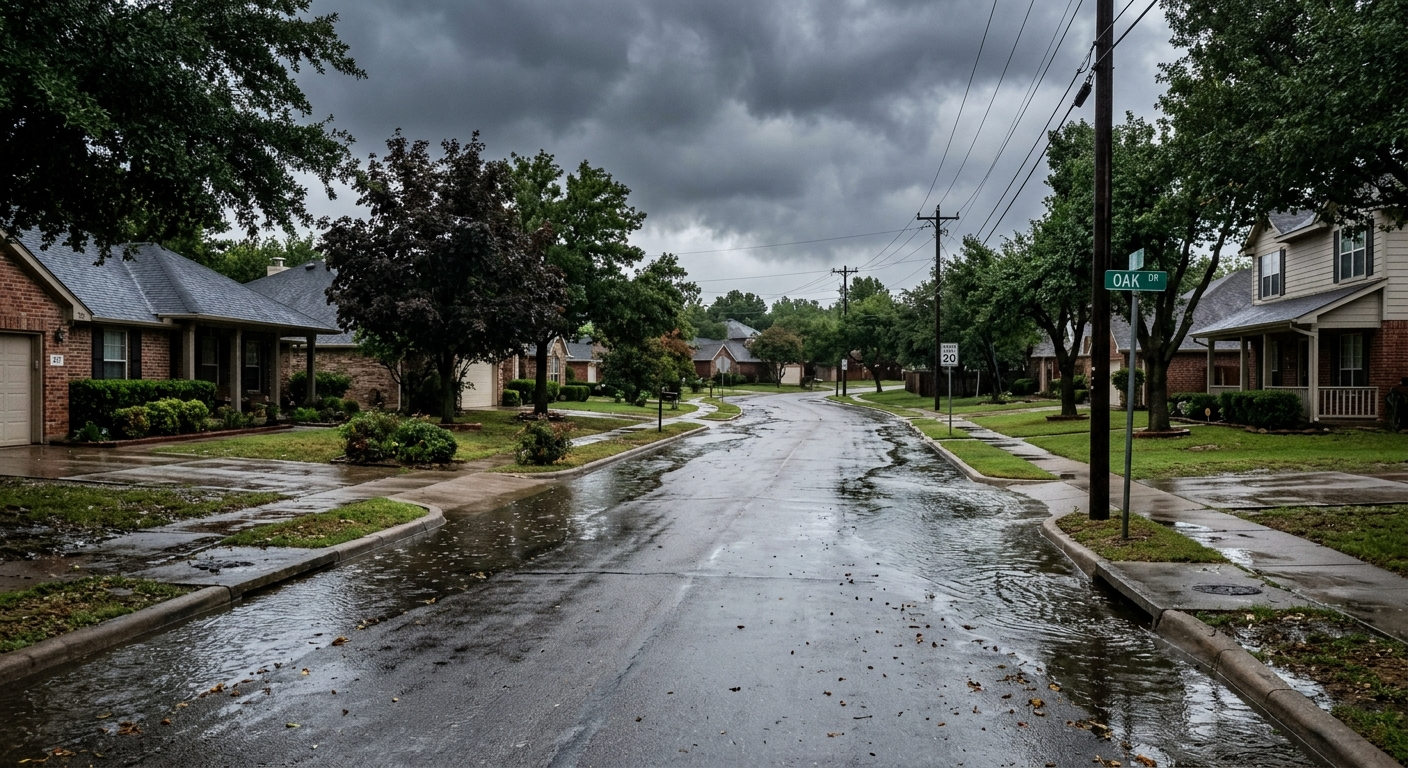
Belton's location along the I-35 corridor puts it in a weather corridor that sees more than its share of wind, hail, and flash flooding every year. Bell County averages roughly 50 severe weather events annually , and hail alone accounts for a significant portion of homeowner claims across the region. The Leon River runs near Belton, and Lake Belton's watershed means properties in lower-lying areas can see water intrusion that catches owners off guard.
Beyond weather, Belton has seen steady residential growth over the past decade. New construction, older 1970s-era homes near downtown, and a wide range of property values across the city mean coverage needs vary considerably from one street to the next. What works for a neighbor may leave you seriously underinsured.
- Hail and wind damage: Bell County sits in what insurers call Hail Alley, and roof claims here are common after spring storm seasons.
- Flash flooding: Low-lying areas near the Leon River and Belton Lake tributaries can flood quickly, and standard homeowners policies do not cover flood damage.
- Wildfire exposure: Dry summers and drought conditions in surrounding Bell County create real wildfire risk, particularly for homes on larger lots with heavy vegetation.
- Liability on your property: Belton's growth means more foot traffic, contractors, and guests, all of which create liability exposure for homeowners.
What a standard homeowners policy covers in Texas
Texas homeowners policies follow a broad but not unlimited structure. Knowing what is included versus what requires a separate policy or endorsement keeps you from finding out the hard way after a loss.
Dwelling coverage
This is the core of your policy. It pays to repair or rebuild your home's structure if it is damaged by a covered peril: fire, wind, hail, lightning, and certain types of water damage from burst pipes. Texas does not cap replacement cost coverage the way some states do, but you need to make sure your dwelling limit reflects the actual cost to rebuild , not the market value or your purchase price. Construction costs in Central Texas have risen sharply since 2020, and many homeowners who bought five years ago are now underinsured without realizing it.
Personal property coverage
Your furniture, electronics, clothing, and other belongings are covered up to your policy's personal property limit, typically 50-70% of your dwelling limit. High-value items like jewelry, firearms, or collectibles may have sub-limits (often as low as $1,500 for jewelry theft under a standard policy) and may need a scheduled endorsement to be fully protected.
Liability coverage
If someone is injured on your property or you accidentally damage someone else's property, liability coverage pays for legal defense and damages. Standard policies start at $100,000, but given today's litigation environment, carrying at least $300,000 to $500,000 in base liability is worth considering. A personal umbrella policy can extend that protection significantly for a modest additional premium.
Loss of use coverage
If your home becomes uninhabitable after a covered loss, loss of use (additional living expenses) coverage pays for hotel stays, rental housing, and increased food costs while repairs are made. This coverage is easy to overlook until you actually need it.
What most Belton homeowners get wrong about their coverage
A few coverage gaps come up repeatedly when working with homeowners across Bell County. These are the ones that matter most.
Flood insurance is not included
This surprises many buyers, especially those purchasing near Lake Belton or in any area with a floodplain designation. Standard homeowners policies do not cover flood damage . Flood coverage must be purchased separately, either through the National Flood Insurance Program (NFIP) or a private flood insurer. Even if your home is not in a designated high-risk flood zone, Bell County's history of flash flooding makes this worth a serious conversation. Our flood insurance guide for Central Texas walks through your options in detail.
Wind and hail deductibles work differently
Many Texas homeowners policies carry a separate wind and hail deductible, often expressed as a percentage of your dwelling coverage (1%, 2%, or sometimes higher) rather than a flat dollar amount. On a home insured for $350,000 , a 2% wind and hail deductible means you pay the first $7,000 out of pocket before the carrier steps in. That is a number worth knowing before storm season, not after. Our breakdown of wind and hail coverage in Central Texas explains how these deductibles work and when they apply.
Replacement cost versus actual cash value
Actual cash value (ACV) coverage subtracts depreciation from your claim payout. If your 15-year-old roof is destroyed by hail, an ACV policy might pay only a fraction of what a new roof costs. Replacement cost value (RCV) coverage pays what it actually costs to replace the item today. The premium difference is usually modest; the claim difference can be tens of thousands of dollars.
Coverage limits that have not kept pace with inflation
If you bought your Belton home several years ago and have not updated your policy since, your dwelling limit may be based on outdated construction costs. Texas has seen material and labor costs jump significantly since the pandemic. An annual review of your coverage limits is basic protection, not an optional task.
How to compare home insurance rates in Belton
Texas is one of the most competitive homeowners insurance markets in the country, but not all carriers offer equivalent value. Rates for the same home can vary by hundreds of dollars per year depending on the carrier's underwriting guidelines, your claims history, your home's age and construction type, and what credits you qualify for.
A few things that directly affect your premium in Belton:
- Roof age and material: Carriers price older roofs significantly higher, and some will not write certain policies on homes with roofs over 15-20 years old.
- Credit score: Texas allows insurers to use credit-based insurance scores, and this factor can move your premium meaningfully in either direction.
- Claims history: Even a single claim in the last three to five years can affect your rate or limit your carrier options.
- Home construction: Frame versus masonry, foundation type, and square footage all factor in.
- Discounts: Bundling your auto and home with one carrier, installing a monitored security system, maintaining a claims-free record, or being a newer buyer can all reduce your premium. See a full list of available home insurance discounts in Texas.
Working with an independent agency means you are not locked into one carrier's pricing. An independent agent can run quotes across multiple companies simultaneously and find the combination of price and coverage that makes sense for your specific home and situation.
Belton-specific coverage considerations
A few local factors are worth flagging for Belton homeowners specifically.
Proximity to Lake Belton
Homes near Lake Belton are popular for good reason, but water proximity brings its own coverage questions. Boat owners, watercraft users, and homeowners with docks may need additional coverage beyond a standard homeowners policy. If you keep a boat on the lake, a separate marine policy or watercraft endorsement is worth reviewing.
Older homes in historic Belton
Belton's older neighborhoods, particularly around the historic downtown area, include homes built before modern building codes were in place. These homes can be more expensive to insure because older electrical systems, plumbing, and construction methods often do not meet current standards. Some carriers will require updates before binding coverage; others will write the policy with exclusions. Knowing this going in helps you shop more effectively.
New construction on the city's edges
Belton's growth has pushed new subdivisions into areas that may carry higher wildfire risk or sit farther from fire stations, both of which factor into underwriting decisions. Builders risk coverage during construction is a separate product from a standard homeowners policy, something to keep in mind if you are building rather than buying.
Get the right home insurance for your Belton home
Winkler Insurance Agency is an independent agency serving Belton and the surrounding Bell County area, including Temple, Harker Heights, and Killeen. Because we are independent, we work with multiple carriers rather than just one, which means we compare rates and coverage on your behalf instead of steering you toward a single company's product.
Whether you are a first-time buyer trying to understand what your lender requires, a longtime homeowner wondering if your limits have kept pace with rising construction costs, or someone who just had a claim and wants to make sure you are better protected going forward, we can help you put together a policy that fits your home and your budget.
Call us at 254-771-5600 or contact Winkler Insurance Agency online to get a home insurance comparison for your Belton property. We will walk through your current coverage, identify any gaps, and show you what options are available: no pressure, just clear answers.
Get A Quote
At Winkler Insurance Agency, securing your future is simple. Ready to protect what matters? Contact us for a quick quote!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.